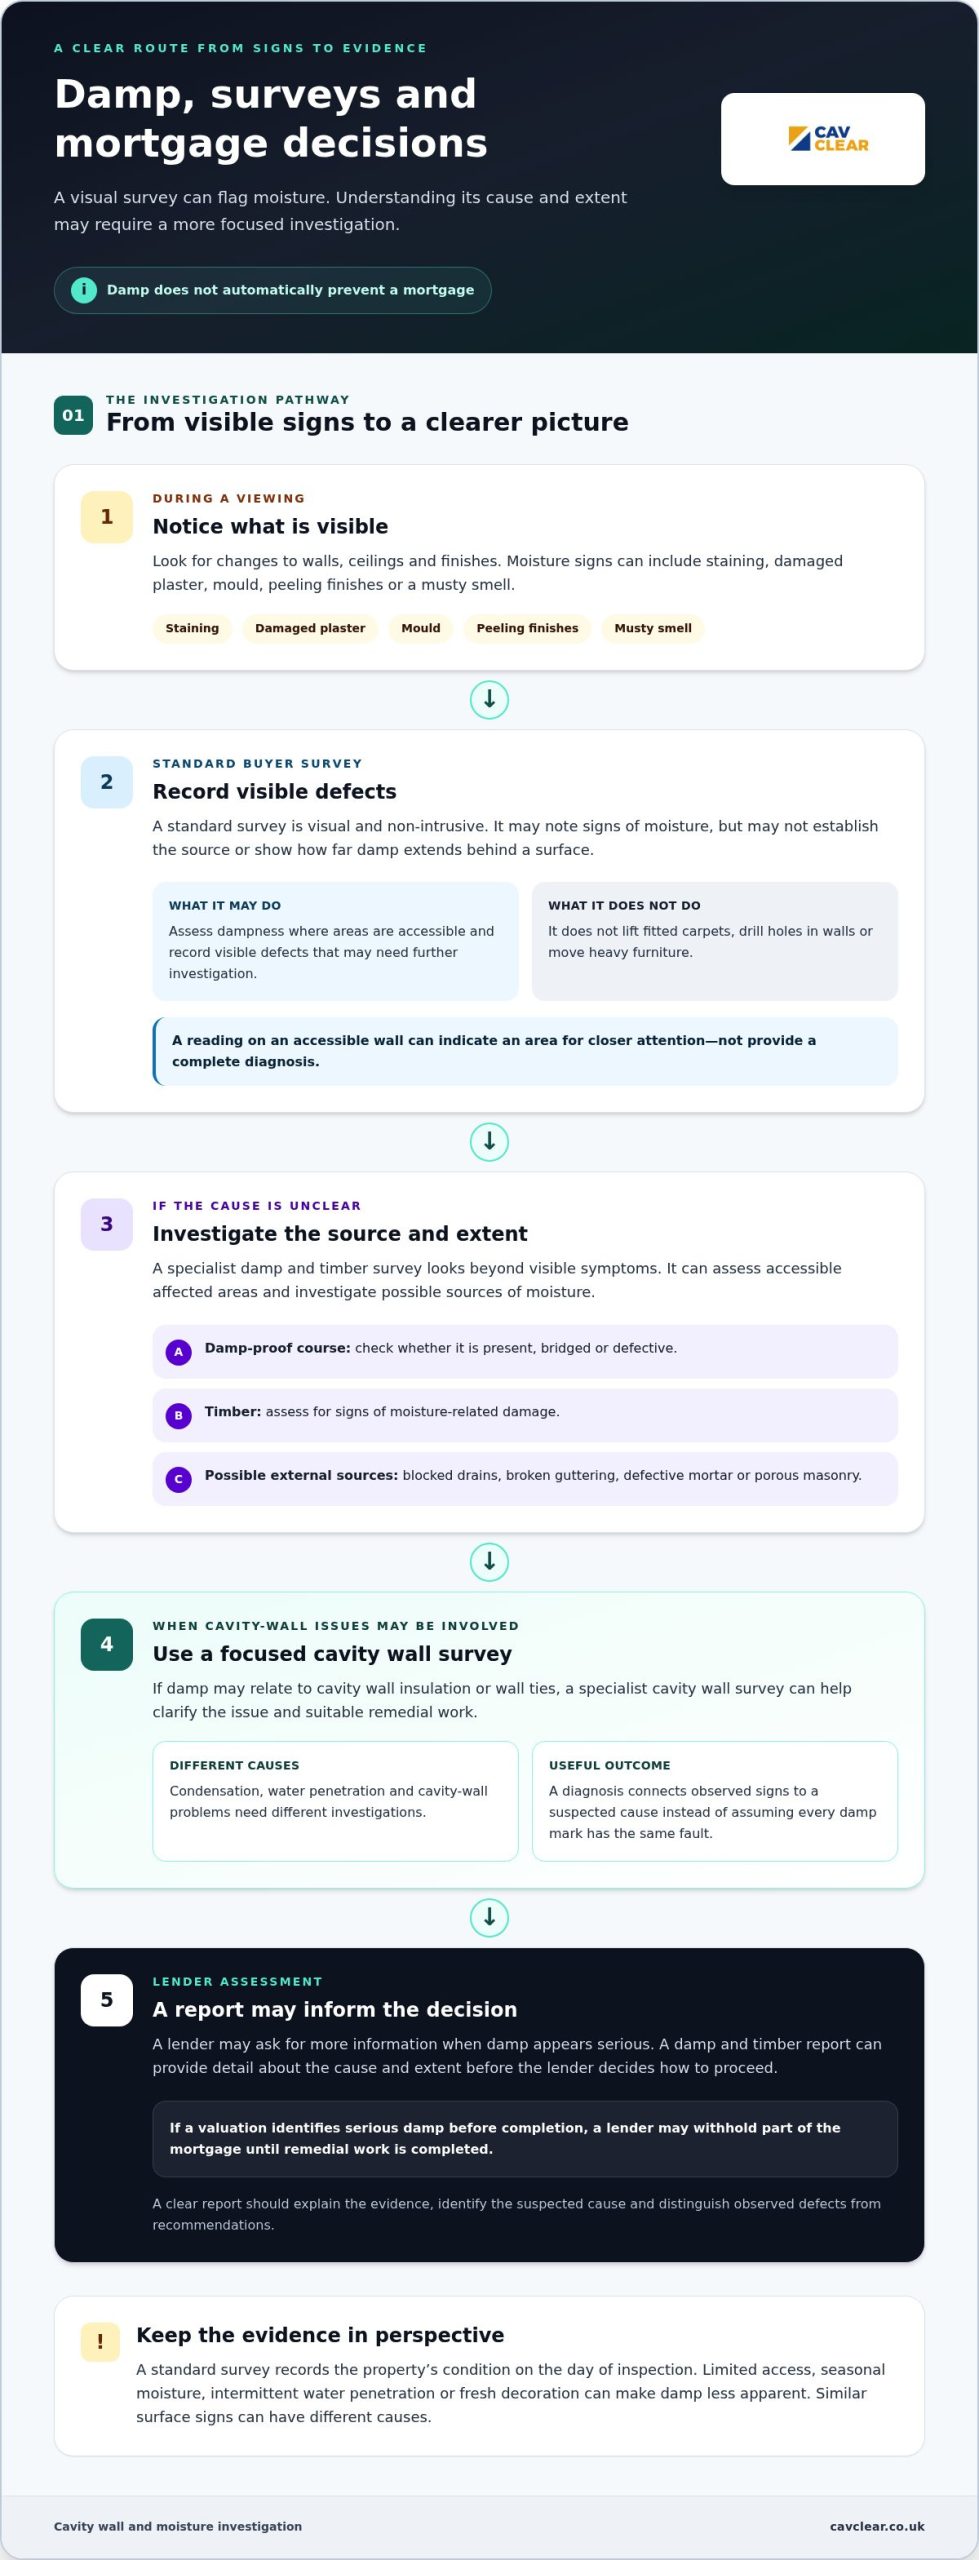
Damp does not automatically prevent a mortgage. You can get a mortgage on a house with damp issues, but a lender may ask for more information if the problem appears serious, such as a damp and timber report, before deciding how to proceed.
Visible staining or a musty smell can be worrying, especially when you’re buying a home and don’t yet know what is causing it. The key question is not simply whether damp is present, but how extensive it is and whether it points to a defect that could affect the property.
This article explains what standard buyer surveys and property viewings may reveal, what lenders look for when damp is reported, and why they may request a specialist report. It also explains why the cause matters: condensation, water penetration and cavity-wall problems need different investigations. A clear diagnosis can help you understand the issue and decide on next steps.
Key Takeaways
- Damp doesn’t automatically prevent a mortgage, but its cause, extent and effect on the property can influence a lender’s decision.
- A standard buyer survey is visual and non-intrusive, so it may identify signs of damp without establishing the full cause.
- Look for changes to walls, ceilings and finishes during viewings, and consider whether the pattern suggests moisture entering from inside or outside.
- Defects such as damaged guttering, blocked drains or failing mortar can allow water to penetrate and may need investigation.
- If damp may relate to cavity wall insulation or wall ties, a specialist cavity wall survey can help clarify the issue and suitable remedial work.
What standard home buyer surveys check for damp
A standard home buyer survey can include checks for visible signs of moisture. The surveyor may note staining, damaged plaster, mould, peeling finishes or musty smells. These observations can indicate damp, but they do not always establish its source or show how far it extends behind a surface.
A RICS Level 3 Building Survey is the most comprehensive standard home buyer survey. It assesses dampness where areas are accessible and records visible defects that may need further investigation. Like other standard surveys, it’s non-intrusive: the surveyor won’t lift fitted carpets, drill holes in walls or move heavy furniture. A reading on an accessible wall, for example, can indicate an area for closer attention, not provide a complete diagnosis.
Limited access can matter when damp is hidden behind furniture, floor coverings or plaster. An inspection also records the property’s condition on that day. Seasonal moisture or intermittent water penetration may be less apparent during a dry spell, while fresh decoration can conceal earlier staining. Different types of damp can produce similar surface signs, so visual evidence alone may not distinguish condensation from water entering through a defect.
A specialist damp and timber survey investigates the cause, rather than relying only on visible symptoms. The surveyor may check whether a damp-proof course is present, bridged or defective, and assess timber for signs of moisture-related damage. The inspection may also consider blocked drains, broken guttering, defective mortar and porous masonry. These checks help connect a damp patch to a possible source, such as rainwater entering through damaged external mortar.
If a lender requests a damp and timber report, review the surveyor’s qualifications and relevant trade association membership. Check that the report explains the evidence, identifies the suspected cause and distinguishes observed defects from recommendations. A useful report should cover affected rooms and accessible surfaces, put moisture readings in context, and explain what further investigation may be needed. A clear diagnosis should focus on the building’s condition, rather than assume a treatment before identifying the cause.
In the UK, damp survey and treatment costs depend on the property, the investigation required, the cause and the work needed. A survey of one affected room differs from a wider timber investigation, while treatment depends on the defect identified.
Buyers usually arrange a specialist investigation before exchange if the standard survey identifies a concern. The report can clarify whether the issue involves internal moisture, external water penetration, timber or a damp-proof course, and whether further inspection is appropriate. It gives the lender and buyer more specific information than a general survey finding, without treating every damp mark as evidence of the same fault.
How serious is damp in a house?
Damp can range from a localised defect to widespread moisture affecting several rooms or building materials. Its extent and cause matter to a lender assessing the property and to a buyer considering the work involved.
For repairs, a practical distinction is whether the purchase has completed. Before completion, agree with the seller who will arrange and pay for any remedial work; after completion, the new owner usually arranges repairs. Set out any agreed work and timing clearly in the sale arrangements.
Damp and Mortgage Approval
Damp can affect a mortgage decision if its severity raises concerns about the property’s condition or use. A mortgage may still be available, but a lender could ask for evidence about the cause and extent before assessing the risk.
A lender may consider the severity of damp or mould when assessing a mortgage application. If a valuation identifies serious damp before completion, a lender may withhold part of the mortgage until remedial work is completed. This can affect the funds available to complete the purchase, so establish what work or reports the lender requires.
One damp patch does not automatically show the full extent of a problem. Rising damp, water penetration and condensation have different causes, and a serious finding needs investigation before you decide whether the property suits your plans. An independent report can distinguish observed damage from a suspected cause. For example, staining near the base of a wall may prompt checks of the damp-proof course and nearby ground levels, rather than an assumption that one treatment will resolve it.
Damp and Sale Price
Damp can affect a property’s sale price because buyers may factor in investigation, remedial work and uncertainty about hidden damage. Established damp problems are estimated to reduce a UK home’s final sale price by around 10%, although the impact depends on the cause and extent.
A report gives both parties a clearer basis for discussing the problem. If rising damp is suspected, for example, an independent assessment can establish whether the damp-proof course is faulty, bridged or absent. The diagnosis may change how buyers assess the work compared with a general survey note that simply records moisture.
Before proceeding, compare the survey findings with the proposed action. Ask whether the affected area is limited or widespread, whether timber is involved and whether the cause has been identified. If the seller agrees to arrange repairs, clarify what work will be done and what evidence will be provided. If the buyer takes responsibility, allow for investigation and remedial work when assessing the purchase.
Sellers should respond clearly when a buyer raises damp and share relevant reports or repair details. Buyers should not treat a seller’s description as a diagnosis: a suggested remedy and an independent survey finding may differ. If the problem remains serious or unexplained, take time to understand its extent before committing to a purchase. That puts the decision on evidence, not just visible plaster damage or a single damp-meter reading.
Signs of damp to look for during property viewings
A viewing lets you assess visible signs, not diagnose the cause. Check each room, including corners, window reveals, chimney breasts and the base of external walls. A dark patch beside a window, for example, may indicate a different moisture route from staining low down on an internal wall. Note its exact location so you can compare it with the building’s exterior later.
Look closely at wall finishes. Peeling wallpaper, bubbling paint, flaking plaster or a powdery deposit can indicate moisture affecting that surface. Rising damp may leave a watermark up to 1m high, but a mark alone doesn’t confirm rising damp. Record whether the affected area appears isolated or continues along the wall, and whether nearby plaster looks damaged too.
Check ceilings and the upper parts of walls for brown marks, peeling finishes or localised discolouration. A patch beneath a roof junction, chimney or upstairs bathroom could be caused by water entering from above. Compare the mark with the room layout: a bathroom or pipework on the floor above may help identify where further investigation should focus.
Notice smells and visible mould, especially in colder corners, behind curtains and around window frames. Condensation can leave droplets on glass and black spotting on nearby seals or paint. Those signs differ from a stain spreading down from a ceiling, although more than one source of moisture can affect the same room. A musty smell without a visible patch is still worth recording.
During your inspection, keep a simple room-by-room record rather than relying on memory. Note the affected wall or ceiling, the finish, the mark’s size and shape, and nearby features such as a window, radiator or drainpipe. Record any freshly repainted areas too. A new finish can make an older stain harder to assess, so ask whether earlier photographs or reports are available.
- At low level: note tide marks, blistered plaster or damaged skirting.
- At openings: inspect window corners, frames and the wall below each sill.
- At high level: look for ceiling stains near roof edges, chimneys and bathrooms.
- Across rooms: compare similar walls and note whether marks recur in adjoining spaces.
Then compare internal signs with visible external conditions, such as a leaking downpipe beside the same wall. This connection can help explain where water may be entering. Do not assume damp-proofing treatment is necessary from a viewing alone; establish the cause before considering remedial work. If staining, mould or damaged plaster appears extensive, include those observations when arranging a fuller property assessment.
Patterns matter more than a single isolated mark. A small patch beside a window may have a local cause, while repeated staining across connected walls suggests a wider issue to investigate. Keep your notes factual: describe what you saw, where you saw it and how the surface looked. These details help a surveyor assess the property and decide whether further inspection is warranted.
External defects that may cause water penetration
Penetrating damp occurs when moisture passes through an external part of the building and reaches internal surfaces. During a purchase assessment, compare indoor staining with the wall, roof or fitting outside. A mark below a gutter, for example, may indicate a different entry route from damp beside a chimney breast. The visible patch shows where moisture appeared, not necessarily where it entered.
Rainwater goods are a practical starting point. Broken guttering can spill water against masonry, while a leaking downpipe can repeatedly wet one section of wall. Check joints, brackets and outlets for visible damage or overflow marks. A blocked drain can also cause water to collect near the building. If an internal damp area is beside these defects, record the locations together for further investigation.
Look at the condition of the external wall itself. Cracked or defective mortar can leave gaps where rain reaches the masonry, while porous brickwork may absorb moisture. Pay attention to damaged pointing around windows, doors and wall junctions. Record a narrow crack near an internal damp patch, but remember that its appearance alone cannot establish how deep it runs or whether it is the source.
Roof details can provide a separate route for water. Missing or damaged roof coverings, defective flashing around a chimney, and poor junctions between extensions and the main building can let water inside. Look for a corresponding ceiling stain or upper-wall mark during the viewing. This relationship helps a surveyor investigate the relevant area instead of treating every internal mark as a ground-level problem.
Ground levels also matter where they meet the wall. Soil, paving or other surfaces raised against masonry can expose the lower wall to persistent moisture and may bridge the damp-proof course. Note whether the external surface sits unusually high beside the affected room. The question is whether moisture has a clear path across or around the damp-proof course, not simply whether a surface looks close to the wall.
Cavity walls introduce further factors. Defective or poorly installed cavity wall insulation can become damp or allow moisture to cross the cavity, particularly if water enters through external masonry. A cavity bridge can also form when mortar or debris connects the outer and inner leaves. Internal damp alongside damaged brickwork or cracking may warrant a cavity wall investigation, including an assessment of the cavity and wall ties.
- Match locations: compare each internal mark with nearby gutters, drains, cracks and roof junctions.
- Record evidence: photograph visible defects and note the affected room and wall.
- Separate observations from diagnosis: describe the defect without assuming it explains every damp patch.
One external defect may explain local moisture, while several defects can affect different parts of a property. During a purchase, a specialist inspection can assess the relationship between the external condition, cavity and internal damage. A report identifying the suspected entry route gives a clearer basis for deciding what further investigation or remedial action is needed.
Mortgage lenders requiring damp and timber reports
UK mortgage lenders assess damp reports by considering the suspected cause, affected areas, severity and recommended action. A damp survey is not a strict requirement for mortgage approval, but a lender may request one if its valuation identifies concerns.
When Lenders Require Damp Reports
A lender may ask for a damp and timber report if a valuation raises questions about moisture, timber condition or repairs. The report helps explain whether the issue appears localised or affects several parts of the property.
For example, staining on an external wall may prompt investigation of both penetrating damp and the wall’s construction. If serious damp is identified before completion, the lender may withhold part of the mortgage until remedial work is completed. This can change the funds available to complete the purchase.
Lender Assessment of Damp Reports
A lender uses the report to understand the evidence behind the damp finding and the recommended work. Clear descriptions of affected rooms, timber condition and likely moisture sources help distinguish a defined repair from a problem whose extent remains uncertain.
For example, a report linking moisture to broken guttering gives a more specific explanation than one that records damp without identifying a possible cause. The lender can consider the severity and proposed action when assessing the property’s mortgage risk.
Useful reports connect indoor findings with relevant building details, which may include external walls, defective mortar, porous masonry, blocked drains or broken guttering. If timber is affected, the report should describe its observed condition and explain what further work or investigation is recommended. This gives the lender information about both the damp and any associated deterioration.
Buyers should read the report alongside the valuation, rather than treating either document as a complete account on its own. A valuation may flag a concern without establishing its source. A specialist damp and timber survey can investigate the suspected cause, while the lender’s request indicates what information it needs to assess the mortgage.
Before arranging further work, identify the lender’s specific concern. Is it the source of moisture, the condition of timber, the affected area or the remedial work needed? A focused report addressing those points can reduce uncertainty. If damp appears alongside cracking to brickwork, a cavity-wall investigation may also help assess whether the cavity or wall ties need attention.
Keep the report, valuation findings and any remedial recommendations together. If the lender asks for further details, those documents help clarify what has been observed and what action is proposed. For concerns involving the cavity or wall ties, discuss a cavity wall inspection to help establish the condition of the wall system.
CavClear: Cavity Wall Insulation Removal
CavClear investigates cavity-wall problems when damp findings point to defective insulation, cavity bridging or wall-tie concerns. Cavity wall surveys assess the wall system, while Wall Tie Surveys can identify failing or corroded ties that may contribute to cracking or movement.
Where defective cavity wall insulation is linked to moisture issues, cavity wall insulation removal addresses the insulation within the wall cavity. The appropriate work depends on the survey findings and the property’s condition. A clear assessment can help buyers understand the defect and consider suitable remedial action alongside any information requested by a mortgage lender.
If damp concerns may involve the cavity or wall ties, contact CavClear to discuss the property and its survey findings.
Make your next property decision with clearer evidence
If you’re asking whether you can get a mortgage on a house with damp issues, focus on understanding the building, not just the visible marks. A clear view of the cause helps you discuss the property with your lender and decide what needs attention before moving forward.
Where evidence points to a cavity-wall problem, CavClear provides Cavity Wall Insulation Removal, Wall Tie Surveys and Wall Tie Replacement. These services address specific cavity-wall and wall-tie concerns, rather than treating every damp symptom as the same fault.
Share your survey findings and property concerns with CavClear to discuss a suitable next step. Contact CavClear about damp issues and move forward with a clearer understanding of the property.
Frequently Asked Questions
What is rising damp?
Rising damp is moisture moving upwards through masonry from the ground. It may leave a tide mark, damaged plaster or salt deposits near the base of a wall. A watermark can reach up to 1m high, but its height alone doesn’t confirm the cause. For example, a low-level mark beside a leaking pipe may have a different source. A survey should consider the wall’s condition and damp proof course.
What Happens If Damp Is Found Pre-Exchange?
If damp is found before exchange, arrange a specialist investigation to establish its cause and extent before deciding how to proceed. A report can distinguish a confirmed defect from a suspected one and identify whether timber or external masonry needs attention. You can then discuss the findings and proposed remedial work with the seller. For example, a report may show that staining relates to a leaking gutter rather than a failed damp-proof course.
What are the main issues that cause damp to rise?
Rising damp can result from a failed, bridged or absent damp-proof course. The course may be made from bitumen, plastic or slate. A bridge occurs when another material creates a route for moisture around the barrier, such as raised ground against the wall. These conditions need to be distinguished from penetrating damp, which enters through an external defect, and condensation, which forms indoors.
Can you get a mortgage on a UK house with damp?
Yes, you can get a mortgage on a house with damp issues, although a lender may ask for more information before assessing the property. The key distinction is between a visible sign and an established cause with known remedial needs. For example, a survey noting a damp patch without explaining it may prompt a request for further investigation. A clear report helps show what is affected and what action is recommended.
What types of damp make a property unmortgageable in the UK?
There is no damp type that automatically makes every UK property unmortgageable. The concern is the severity and effect on the home: lenders may consider damp or mould severe if it makes the property uninhabitable. A local condensation patch and widespread moisture affecting rooms or building materials present different levels of concern. A report explaining the extent, cause and necessary work gives a more useful basis for assessment than the label alone.
Will a mortgage lender require damp repairs before completion?
A lender may require remedial work before releasing the full mortgage if its valuation identifies serious damp before completion. In that situation, it may withhold part of the loan until the work is complete. This is not an automatic response to every damp finding. For example, a lender may ask for a report first if the valuation records moisture but does not establish whether repairs are needed. Check what evidence or work its decision requires.
Can you get a mortgage on a damp house with a specialist or adverse-credit lender?
A specialist or adverse-credit lender may assess an application, but the property’s damp condition still matters independently of the borrower’s credit history. The lender may want to understand the moisture source, affected areas and remedial recommendations before assessing the property risk. For instance, a detailed report about one isolated defect provides different information from a finding of widespread damp. The lender’s criteria determine how those property findings affect its decision.
What steps should buyers take if a survey finds damp before exchange?
Start by identifying exactly what the survey recorded: location, visible damage and any suspected cause. Then arrange a specialist damp and timber investigation if the finding needs diagnosis. Review the surveyor’s qualifications and trade association membership, and ensure the report explains its evidence and recommendations. Share relevant findings with the lender if requested. Before deciding, compare the investigation results with the proposed remedial work and the property’s condition.
Recent Comments